The disconnect between bearish credit pricing and tight physical feedstock supplies suggests that the 2026 biomass-based diesel market is navigating a period of unprecedented regulatory uncertainty. As the midpoint of the final quarter approaches, the industry finds itself at a critical juncture regarding the Renewable Fuel Standard (RFS) requirements. Currently, the total available supply of 2026-vintage D4 Renewable Identification Numbers (RINs) stands at approximately 5.524 billion credits, which represents just under 64 percent of the annual mandate of 8.686 billion credits. While this figure illustrates a significant volume of fuel already blended into the national supply, it also highlights a substantial deficit that must be addressed before the compliance year ends. Refiners and importers, known as obligated parties, are closely monitoring these benchmarks as the gap between actual production and federal mandates remains wide. This creates a complex environment where regulatory compliance hinges on a late-year surge in manufacturing.
Evaluating Current Production and Supply Gaps
The evaluation of current production benchmarks reveals a sector that is working at maximum capacity to reconcile physical output with ambitious federal goals. As the third quarter of 2026 concludes, the biomass-based diesel industry has demonstrated significant resilience, yet the supply gap remains the defining characteristic of the compliance year. Understanding this gap requires a deep dive into the monthly output trends reported by the Environmental Protection Agency and an analysis of the logistical constraints that govern the fuel supply chain. While the domestic industry has recently hit production highs that suggest a robust recovery, the sheer volume of D4 Renewable Identification Numbers required to meet the 8.686 billion annual target creates a sense of urgency for refiners. The following analysis explores how the industry is managing this shortfall, focusing on the specific performance of biodiesel and renewable diesel alongside the tightening availability of key agricultural feedstocks.
Monthly Output Trends and the Production Shortfall
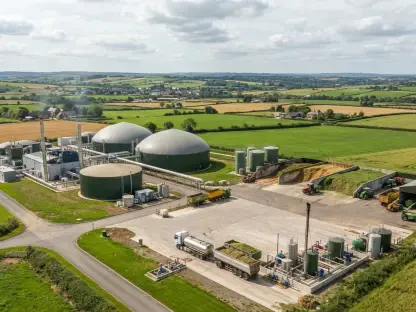
Data provided by the Environmental Protection Agency’s Moderated Transaction System (EMTS) for September 2026 suggests that domestic production is finally gaining the momentum required to challenge these federal targets. During that month, the industry generated 788.1 million D4 RINs from 483.0 million gallons of fuel, marking a ten percent increase over the previous month and reaching the third-highest monthly output of the current calendar year. Domestic biodiesel specifically hit a peak of 142 million gallons, a level of performance that has not been observed in over two years. Renewable diesel also maintained a strong trajectory, contributing 294.7 million gallons to the national total. However, the renewable jet fuel sector did not share in this growth, experiencing a sharp thirty percent decline in production to roughly 21.6 million gallons. This mixed performance underscores the uneven nature of the domestic transition toward cleaner fuels.
The Role of Feedstock Availability and Supply Chain Constraints
The feasibility of reaching these heightened production levels is intrinsically tied to the availability and pricing of raw materials, particularly soybean oil. Information from the National Oilseed Processors Association (NOPA) indicates that the feedstock market is currently facing a period of notable tightening, which could limit further production gains. September crush volumes reached their lowest point in over a year, while domestic soybean oil inventories dropped to approximately 1.05 billion pounds. This represents the lowest inventory level recorded for this specific feedstock in over a decade, signaling that there is very little excess supply available to fuel a massive surge in biomass-based diesel production. Without a significant buffer in feedstock stocks, any disruption in the supply chain or a further decrease in crush volumes could immediately hinder the industry’s ability to produce the volume of fuel required by the RFS mandates. This constraint remains a primary concern for refiners.
Regulatory Influences and Market Dynamics
Beyond the physical constraints of production and feedstock availability, the biomass-based diesel market is being fundamentally shaped by a complex set of regulatory variables and shifting consumption forecasts. The management of the Renewable Fuel Standard is not merely a matter of fuel volume; it is an intricate dance of credit generation, small refinery exemptions, and long-term energy projections provided by federal agencies. These regulatory shifts often have a more immediate impact on market sentiment than physical supply changes, as they dictate the future obligations of refiners and importers. To fully grasp the current state of the market, it is essential to examine the recent decisions regarding refinery exemptions and how the reallocation of these volumes influences the demand for compliance credits. Additionally, the revised consumption outlooks from energy analysts provide a broader context for the growth of the renewable fuel sector relative to traditional diesel markets.
Small Refinery Exemptions and Reallocation Challenges
A major variable in the demand for RINs is the management of Small Refinery Exemptions (SREs) by the Environmental Protection Agency. In late August, the agency granted 29 refineries either full or partial exemptions for the previous compliance year, which totaled approximately 1.76 billion RINs. Because the federal government had only projected a fraction of this volume when setting the current standards, an additional 770 million RINs must now be accounted for to maintain the integrity of the program. The EPA is currently evaluating whether to reallocate this entire volume into the 2027 compliance year or split the burden between the current year and the next. This decision is critical because any reallocation effectively increases the amount of renewable fuel that obligated parties must blend into the fuel supply or cover through credit purchases. The market is currently in a state of watchful waiting, as the final decision will dictate the urgency of RIN acquisition.
Shifting Federal Consumption Forecasts and Trade Dynamics
Simultaneously, the Energy Information Administration (EIA) has adjusted its short-term energy outlook, presenting a more conservative view of biomass-based diesel consumption. In its October report, the EIA increased projected traditional diesel consumption while cutting biomass-based diesel projections by significant margins for both this year and the next. For the upcoming year, the revision was even more pronounced, with a substantial cut to the expected use of renewable diesel and biodiesel. These figures suggest that while the consumption of renewable fuels is still growing, the rate at which they are gaining market share is slower than analysts previously anticipated. This divergence between federal mandates and projected consumption creates additional pressure on the credit market, as obligated parties must navigate a landscape where physical blending may not naturally meet regulatory requirements. This shift in forecasting reflects the complex balance between petroleum and renewable fuel sectors.
Economic Paradoxes and Future Strategic Compliance
The intersection of regulatory policy and physical supply has created a unique economic environment characterized by several paradoxes in credit pricing and producer incentives. In a traditional market, a looming supply deficit would typically lead to a surge in prices, yet the biomass-based diesel sector has recently seen the opposite effect in its credit markets. This anomaly highlights the disconnect between speculative sentiment and the underlying economic health of the refining industry. Understanding this dynamic requires an analysis of the “BOHO spread” and how the relative strength of the broader energy market provides a financial buffer for producers even when regulatory credits are losing value. Furthermore, the strategic use of banked credits from previous years serves as a critical stabilization mechanism, allowing the industry to navigate periods of uncertainty without immediate crises. The following sections explore these economic complexities and the long-term strategic decisions facing obligated parties.
The RIN Price Mystery and Market Sentiment
One of the most surprising trends in the current market is the decline in RIN prices despite the apparent supply deficit. Following the release of the September production data, credit values for both renewable fuel and biomass-based diesel saw unexpected drops, with some benchmarks falling several cents in a single day. This price action has been described by industry participants as a major head-scratcher, as traditional supply-and-demand logic would typically dictate higher credit prices when production lags behind mandates. Several factors may explain this bearish sentiment, including buyer hesitancy as refiners wait for the finalization of the SRE reallocation rules. Additionally, falling values for similar fuels in European markets may be reducing the incentive for exports, potentially keeping more RIN-generating fuel within domestic borders. This disconnect between credit pricing and physical supply realities highlights the speculative nature of the current regulatory compliance market.
Producer Margins and the Impact of Energy Prices
Despite the volatility observed in the credit markets, the underlying economics for biomass-based diesel producers have remained relatively stable. This stability is largely due to the narrowing of the price difference between soybean oil and heating oil futures, commonly referred to as the BOHO spread. As diesel futures strengthened, the overall energy market provided a buffer that offset the loss in RIN value, keeping the biodiesel margin proxy around $2.70 per gallon. This figure is significantly higher than the median observed earlier in the year, suggesting that producers are still finding profitable opportunities despite the regulatory uncertainty. The strength of traditional energy prices has effectively subsidized the renewable sector during this period of transition, allowing refiners to maintain high output levels even when credit prices are under pressure. This economic resilience is a key factor in the industry’s ability to maintain its recent production momentum amid feedstock tightening and global volatility.
Path Forward: Navigating the Regulatory Horizon
The United States biomass-based diesel industry navigated a complex landscape throughout 2026, balancing record-setting production months against a persistent regulatory deficit. Stakeholders observed that while the domestic refining capacity remained robust, the physical limitations of the feedstock market and the ambiguity of federal reallocation rules created a unique set of challenges. To ensure long-term stability, it is recommended that market participants prioritize the diversification of feedstock sources beyond soybean oil to mitigate the risks of localized shortages. Furthermore, closer alignment between federal consumption projections and the reality of credit generation will be necessary to prevent the price paradoxes that defined the current year. As the industry transitioned into the 2027 compliance cycle, the lessons learned from the 2026 supply gap emphasized the need for a more transparent and predictable regulatory framework. Ultimately, the successful management of banked credits and production incentives served as the bridge to a more sustainable energy future.