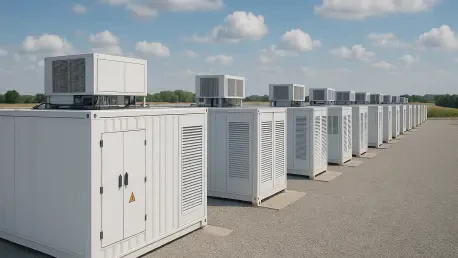
The European energy storage market is bracing for a massive influx of inventory as Chinese manufacturers accelerate shipments before a critical export tax rebate disappears in early 2027. This surge comes at a juncture where the continent is already struggling to reconcile its ambitious green energy targets with the logistical realities of global trade. Recent data from industry analysts suggests that Chinese manufacturers maintain a vertically integrated stronghold over the battery value chain, controlling between 70% and 95% of everything from raw material processing to cathode production. This dominance is not merely a matter of volume but one of profound cost efficiency that European competitors find increasingly difficult to match. As the industry progresses through 2026, the focus is shifting toward how these manufacturers are front-loading shipments to avoid upcoming fiscal changes. This inventory glut is expected to saturate European warehouses for the remainder of the year.
Supply Chain Dynamics and Policy Shifts
The Catalyst: Export Rebate Reductions
The primary driver behind the current shipment surge is a fundamental change in Chinese fiscal policy concerning export tax rebates. Currently, battery products exported from China benefit from a 9% rebate, but this incentive is scheduled to decrease to 6% before being phased out entirely by the start of next year. This regulatory deadline has triggered a massive ‘pull-forward’ effect, where manufacturers are incentivized to move as much finished inventory as possible into international markets while margins remain protected. This strategy is effectively detaching shipment volumes from actual real-time demand within Europe. Consequently, the market is seeing a flood of storage components that are likely to exceed the immediate absorption capacity of the European power sector. By moving goods now, Chinese firms are attempting to lock in profits that would otherwise be eroded by the new tax structure, regardless of whether the end-users in Europe are ready for the storage hardware today.
This sudden influx of components is placing immense pressure on European logistics and warehousing infrastructure, which was not originally designed to handle such a concentrated volume of battery storage hardware. As shipments continue to arrive at major ports like Rotterdam and Hamburg, the challenge shifts from procurement to storage and eventual deployment. For many manufacturers, the priority is simply to get the products across the border and onto European soil to qualify for the higher rebate rates. This has led to a situation where the inventory levels in European warehouses are reaching historic highs, creating a buyer’s market for those with the capital to stockpile components. However, for smaller distributors, this glut represents a significant financial risk, as the value of their existing stock could depreciate rapidly if the market becomes overly saturated. The disconnect between policy-driven shipments and demand is the defining economic trend of the 2026 transition.
Vertical Integration: Market Entry Barriers
Chinese dominance in the energy storage sector is rooted in a level of vertical integration that remains unparalleled in the global market. At the earliest stages of the supply chain, Chinese firms control the vast majority of raw material processing, particularly for lithium and cobalt, which are essential for high-performance battery cells. This control extends through the mid-stream production of cathode and anode active materials, where Chinese market share reaches a staggering 95%. Such concentration allows these companies to maintain tight control over production costs and quality, creating a barrier to entry that is nearly impossible for new European entrants to breach. Even as European governments attempt to incentivize domestic manufacturing, the sheer scale and efficiency of the existing Chinese infrastructure provide a competitive edge that is difficult to disrupt. This structural reality ensures that the majority of hardware entering the European market in 2026 originates from a single ecosystem.
As we move further into the 2026 production cycle, the gap between Chinese manufacturing capabilities and European domestic output remains significant. While there are assembly facilities for battery packs in Europe, these often rely on cells manufactured in China, meaning the core value and technological control remain offshore. EUPD Research highlights that battery cell manufacturing continues to be dominated by a handful of Chinese giants who account for 80% to 90% of global capacity. This centralization of production means that any shifts in Chinese industrial policy have immediate and profound ripples across the European energy landscape. For European companies to gain a foothold, they would require not only significant technological breakthroughs but also massive, sustained policy interventions similar to those seen in other major markets. Without such changes, the European market will continue to function primarily as an off-take region for Chinese-made technology as firms rush to export now.
Market Segmentation and Pricing Trends
Divergent Realities: Residential Versus Utility Sectors
The impact of the 2026 inventory surge is manifesting in very different ways across the various sectors of the European storage market. The residential and small-scale commercial and industrial sectors are currently bearing the brunt of the oversupply. These markets typically operate on a ‘push’ model, where products move from manufacturers to large wholesalers and then down to local installers. Because these intermediaries often buy in bulk to ensure availability, they are now finding themselves holding massive amounts of stock that was shipped to beat the tax rebate deadline. This has created a situation where the supply of residential battery systems is vastly outstripping the current installation rate. In contrast, the utility-scale segment operates on a much more disciplined ‘pull’ model. Large-scale battery energy storage systems are generally manufactured against specific, confirmed contracts with pre-defined delivery schedules, which protects that specific market from the volatility.
Because utility-scale projects are planned years in advance and involve complex grid-connection agreements, they are less susceptible to the sudden spikes in inventory that plague the residential sector. These large projects do not rely on the same middleman distribution channels, which means there is no buildup of unallocated stock in third-party warehouses. While residential prices are facing downward pressure due to the need to clear sitting inventory, utility-scale pricing remains relatively buoyant and stable. This bifurcation is creating a unique market environment where high-volume, low-margin residential products are being discounted aggressively, while professional-grade utility hardware maintains its value. For developers of large-scale storage plants, the current shipment surge offers little in the way of immediate price relief, as the specialized components they require are not part of the speculative inventory flood that is currently hitting the broader European distribution market.
Market Outlook: Labor Constraints and Regional Stability
A critical factor that is exacerbating the residential inventory crisis is the limited availability of qualified labor to perform installations. Regardless of how many battery units are shipped from Chinese ports and stored in European warehouses, the actual rate of deployment is capped by the number of certified technicians and electricians. This physical bottleneck means that even if hardware prices drop significantly, the total number of systems coming online cannot exceed the labor force’s capacity. Currently, many European countries are facing a severe shortage of skilled workers in the renewable energy sector, which has led to long wait times for residential storage projects. This mismatch between the abundance of hardware and the scarcity of installation services is preventing the market from reaching an equilibrium. Consequently, the excess inventory continues to sit in warehouses, further driving down the wholesale price as distributors look for ways to recoup capital.
Industry stakeholders recognized that the volatility experienced throughout the middle of the decade provided necessary lessons for future infrastructure development. They determined that relying solely on international fiscal incentives was insufficient for maintaining a stable market, which spurred more robust domestic policy frameworks. As companies moved into the post-rebate era, the focus shifted toward enhancing grid integration and expanding the skilled labor force to match manufacturing output. The surplus inventory that dominated the landscape was eventually absorbed as installation capacities expanded, though the process required a significant recalibration of pricing. Moving forward, the European energy sector prioritized building resilient, localized supply chains that could withstand geopolitical shifts and logistical disruptions. These actions ensured that the transition to renewable energy remained on track, even as the global trade environment became increasingly complex for everyone.