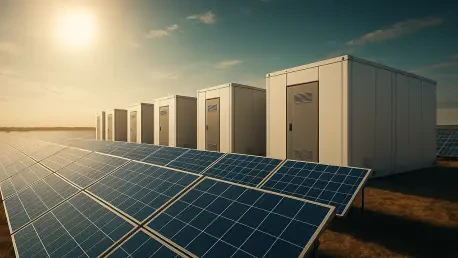
The transition from gas-fired peaking plants to solar and storage integrated systems is no longer a matter of if, but a matter of how quickly grid operators can adapt. Recent global energy assessments reveal that the Levelized Cost of Electricity for four-hour battery storage has officially dipped below the cost of maintaining and operating open-cycle gas turbines in the vast majority of international markets. This economic crossover signifies a profound shift in how power grids manage peak demand, moving away from carbon-intensive thermal assets toward modular, rapid-response electrochemical storage. As global manufacturing scale expands, the price of battery hardware continues to plummet, while gas prices remain susceptible to geopolitical volatility and supply chain constraints. This convergence of affordability and reliability has positioned storage not merely as a backup for intermittent renewable sources, but as a direct competitor to traditional fossil-fuel-based peaking capacity across the globe.
Global Trends: The Divergent Path of Regional Markets
In the Middle East and Africa, the momentum toward solar-plus-storage projects has accelerated significantly due to unrivaled solar irradiation and the development of massive utility-scale projects. In countries like Saudi Arabia and the United Arab Emirates, solar energy costs have dropped to record lows, creating a fertile environment for battery integration. Current projections indicate that the cost of storage in this region will decrease by another 33 percent over the next decade, effectively closing the window for new gas-fired peaking infrastructure. Similarly, Latin American markets are leveraging aggressive procurement mandates to stabilize their grids, expecting a significant plunge in battery costs by the middle of the century. These regions are essentially skipping the traditional natural gas expansion phase, opting instead for a cleaner, more resilient architecture that utilizes lithium-ion and long-duration storage technologies to meet growing industrial and residential electricity requirements.
The Asia Pacific region continues to serve as the global cost anchor, primarily driven by China’s immense manufacturing capacity and domestic supply chains. Storage costs within China remain roughly 55 percent lower than the regional average, exerting downward pressure on prices throughout the continent despite local tariffs in markets like Australia and Japan. Meanwhile, the European energy landscape is undergoing a unique transformation where the cost of carbon emissions is becoming a larger financial burden than the fuel itself. By 2030, analysts expect carbon pricing to make fossil-fuel generation prohibitively expensive, forcing utilities to pivot toward turnkey battery systems to avoid heavy environmental penalties. This trend is reinforced by the rapid deployment of single-axis tracker solar technology, which has become the least expensive source of new generation in nearly 90 percent of surveyed regions. The synergy between cheap generation and falling storage costs is dismantling the old peak gas model.
Strategic Adaptation: Navigating Trade Barriers and Demand Surges
North America presents a stark contrast to the global trend due to persistent trade barriers and protective economic policies that have kept hardware prices artificially high. While international markets benefit from unhindered access to low-cost components, developers in the United States and Canada must navigate a complex web of anti-dumping duties and Section 232 import restrictions. These measures have created a pricing floor for solar modules and battery cells, preventing the same rapid deflation seen in the Eastern Hemisphere. Despite these headwinds, utility-scale developers have managed to mitigate some impacts by safe-harboring substantial capacity, but residential and commercial sectors remain vulnerable to price spikes. Trade policies aimed at bolstering domestic manufacturing are effectively trading short-term cost savings for long-term industrial independence. Consequently, the North American market is currently defined by a delicate balance between policy-driven price supports and cost pressures.
The shift toward battery storage as the primary mechanism for peaking power signaled a fundamental restructuring of the global energy economy. Grid operators and utilities recognized that the era of fossil-fuel dominance for short-duration capacity was ending as storage costs reached a historic tipping point. Moving forward, the focus must shift toward streamlining the interconnection process and optimizing battery management software to maximize the value of these assets. Investing in long-duration energy storage and diversifying chemical compositions beyond lithium-ion will be critical for maintaining grid stability during extended periods of low renewable output. Proactive planning for infrastructure upgrades and the integration of smart grid technologies allowed forward-thinking regions to transition seamlessly. Ultimately, the successful deployment of storage-centric grids depended on balancing local manufacturing goals with the immediate need for affordable decarbonization, ensuring that the next generation of power systems was sustainable.
Stakeholders recognized the importance of prioritizing the development of circular supply chains for battery materials to mitigate potential resource scarcity as global demand intensified. Establishing robust recycling programs and secondary markets for second-life batteries not only reduced environmental impact but also provided a buffer against the price volatility of raw minerals. Furthermore, local governments worked to harmonize permitting processes to reduce the soft costs that previously hindered rapid deployment in many jurisdictions. The transition proved that while hardware costs were a primary driver, the regulatory and logistical frameworks were equally important for long-term success. By fostering public-private partnerships and investing in workforce training for the renewable sector, nations ensured that their energy transitions were both inclusive and durable. These actions demonstrated that the path to a storage-dominant grid required a holistic approach that combined technological innovation with strategic policy reform.