Despite a broader market decline, the D4 biomass-based diesel category has shown relative price resilience because its year-to-date supply represents only 63.6% of annual requirements. This specific dynamic highlights a growing rift in the United States Renewable Identification Number market, which began a sharp repricing phase following the release of Environmental Protection Agency data in mid-October 2026. As participants analyzed the latest Moderated Transaction System figures, it became evident that the surplus of conventional ethanol credits is expanding at a pace that far exceeds current domestic blending capabilities. While the entire renewable fuel credit complex has felt the weight of downward pressure, the D6 category has borne the brunt of the selloff. The premium for biomass-based diesel credits over their conventional counterparts expanded from approximately 7 cents to a notable 12 cents in just one week, signaling a market that is increasingly comfortable with its ethanol-linked inventory.
Analyzing the Conventional Fuel Surplus
Identifying the Drivers of D6 Oversupply
The aggressive decline in D6 RIN values is primarily rooted in a comfortable supply-and-demand balance that has emerged throughout the current calendar year. By the end of the third quarter of 2026, the net supply of conventional credits had reached nearly 73% of the annual requirement, a figure that suggests the market is well ahead of its compliance milestones. With production tracking almost perfectly alongside these annual goals, the scarcity premium that previously supported higher prices has effectively evaporated, leaving the market in a state of relative abundance. Market participants have reacted swiftly to this realization, leading to a significant divestment from D6 holdings as the perceived risk of a supply shortfall diminished. This shift in sentiment is not merely a localized reaction but reflects a broader understanding that the structural constraints once governing the market have significantly loosened in recent months.
Evaluating the Impact of Scarcity Premium Erasure
As the scarcity premium vanished, the financial landscape for obligated parties shifted toward a more conservative procurement strategy. Refiners and importers, who previously hoarded credits to guard against end-of-year shortages, began to release excess inventory into the secondary market, further accelerating the price drop. This behavioral change is indicative of a market that no longer fears a deficit, as the robust generation of credits from corn ethanol production provides a significant buffer. Furthermore, the absence of aggressive bidding has allowed prices to find new, lower floors, which in turn has reduced the overall compliance cost for the industry. While this provides some relief to refiners, it also signals a period of reduced volatility where the primary focus has shifted from securing supply to optimizing the timing of transactions. The resulting price stability at these lower levels suggests that the market has fully priced in the current surplus.
Tracking Industrial Metrics and Inventory Trends
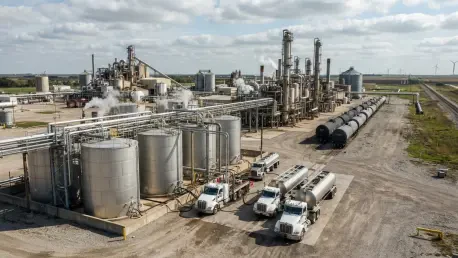
Industrial metrics further support the bearish outlook for ethanol-linked credits, with U.S. ethanol production remaining consistently high. Throughout the latter half of 2026, production levels have frequently exceeded 1.09 million barrels per day, a pace that continues to test the limits of domestic consumption capacity. Simultaneously, domestic stocks of ethanol have climbed to approximately 24.56 million barrels, indicating that supply is significantly outpacing the rate at which fuel is being blended into the gasoline pool. When production levels remain this elevated, the excess fuel must either be absorbed by inventories or pushed into the export market, both of which have limited capacity to handle the current surge. This backup in the physical supply chain directly translates to an overabundance of RINs, as each gallon produced generates a corresponding credit that must eventually find a buyer in a market already saturated with options.
Overcoming the Constraints of the Blend Wall
The primary physical limitation on ethanol consumption remains the traditional 10% saturation point of the gasoline pool, commonly referred to as the blend wall. Because domestic gasoline consumption has not seen a significant uptick to match the surge in ethanol production, the industry is essentially hitting a ceiling on how much renewable fuel can be physically utilized. This constraint creates an inevitable buildup of D6 RINs, as there is limited domestic physical capacity to consume the additional fuel being manufactured. Even as some retailers attempt to push higher blends like E15 or E85, the infrastructure requirements and consumer adoption rates have not moved fast enough to clear the existing surplus. Consequently, the blend wall acts as a permanent barrier that traps excess credits within the system, ensuring that supply continues to outstrip demand unless there is a dramatic shift in either production economics or a sudden regulatory change.
Shifting Consumption and Regulatory Hurdles
Impact of Reduced Gasoline Consumption Trends
A critical factor in the current market selloff is the erosion of demand for renewable fuel credits caused by shifting consumption patterns. The original EPA percentage standards for 2026 were calculated based on an initial forecast of roughly 140 billion gallons of gasoline consumption. However, updated data from the Energy Information Administration suggests that actual gasoline use will likely fall short of those projections by nearly 6 billion gallons. Because the RIN obligation for refiners is tied directly to their actual production and import volumes, a smaller gasoline pool automatically reduces the total number of credits required for compliance. This demand-side contraction has caught some market participants off guard, as they had positioned themselves based on the higher initial estimates. The realization that fewer credits are needed to meet federal mandates has added another layer of downward pressure on D6 prices.
Navigating Regulatory Uncertainty and Compliance Decisions
Market dynamics are also heavily influenced by a lack of clarity regarding Small Refinery Exemptions and the potential reallocation of credits. The EPA has proposed a reallocation of approximately 770 million RINs stemming from past exemptions, but the agency has yet to finalize whether this additional obligation will be applied to the current year or deferred until 2027. This regulatory stalemate has caused many obligated parties to adopt a wait-and-see approach, effectively stifling buying urgency across the board. Without a clear directive on how these extra credits will be handled, refiners are hesitant to make large-scale purchases, preferring to maintain lean positions until the legal landscape is more defined. This listless price action is a direct result of the uncertainty, as the market lacks the necessary catalysts to drive a meaningful recovery in values while these critical decisions remain in a state of flux.
Assessing Production Resilience and Economic Incentives
Interestingly, the decline in RIN prices has not yet triggered a significant slowdown in fuel production, largely due to the strength of the biodiesel margin proxy. Financial incentives for producers remain historically robust, meaning that as long as the margins for manufacturing renewable diesel and biodiesel remain favorable, facilities will continue to operate at high utilization rates. This economic reality prevents the market from self-correcting through supply contraction, as producers are motivated by the profit potential of the fuel itself rather than the value of the associated credit. As a result, the supply of RINs continues to grow even as their market value diminishes, creating a feedback loop that sustains the current downward price trend. This resilience in production highlights a decoupling of fuel manufacturing from credit pricing, where the underlying commodity economics dictate the pace of supply more than the regulatory incentives.
Forward-Looking Strategies for Market Participants
In conclusion, the RIN market demonstrated a clear transition from a period of perceived scarcity to one of relative abundance as the year progressed. Stakeholders prioritized efficiency over speculative hoarding as data confirmed a robust supply buffer for conventional fuels, which allowed for a recalibration of compliance costs across the industry. Those managing complex credit portfolios shifted their focus toward long-term hedging strategies to mitigate the impact of the current price volatility and to prepare for potential regulatory shifts. It remained essential for participants to monitor upcoming EPA announcements regarding Small Refinery Exemptions to anticipate changes in total obligation volumes. The market successfully adapted to the new pricing reality by aligning inventory levels with actual gasoline consumption trends rather than original forecasts. Moving forward, a focus on infrastructure for higher ethanol blends could provide the necessary relief to clear the existing credit surplus and stabilize the conventional fuel market.